• Case ID: #26
  • Primary Personality Archetype: 🌱 The Steward (Rigidity Bias)
  • Systemic Risk: Access Impediment (The Landlocked Legacy)
  • Financial Impact: 60% Valuation Wipeout / $200,000 Legal Fee Erosion
  • Jurisdiction: Federal / National (Australian Property Law)
  • Verification: Property Litigation Review / Registry Archive #26
Reading Time: 2 minutes

Case File #26: The Landlocked Legacy

The Unregistered Right

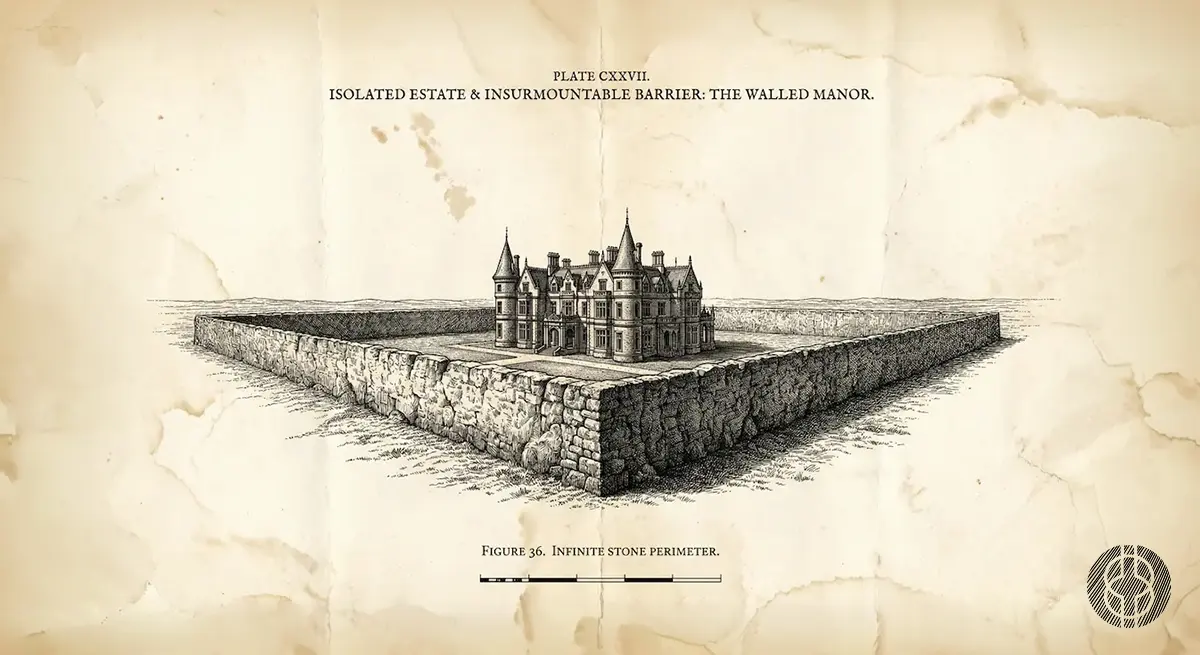
Old Man Miller had used the same dirt track to reach his back paddock for forty years. It crossed a small corner of his neighbor’s land, but they were friends; a handshake was enough. When the neighbor died and the land was sold to a corporate ag-firm, the handshake died with him.

The new owners put up a steel gate and a 'No Trespassing' sign. Miller argued he had a right of way, but it wasn't on the title. The 'Torrens Title' system in Australia is cold: if it isn't registered, it rarely exists. Miller’s back paddock, now inaccessible, dropped 60% in value. He spent his final years and $200,000 in legal fees fighting for a driveway he thought he already owned.

  • Clinical Mystery: Why was an inherited multi-million dollar property impossible to sell?
  • The Human Intent: To keep the family estate 'whole' by forbidding any one sibling from selling their portion
  • The Diagnosis: The Restraint on Alienation: You cannot legally 'lock' an asset forever; the law demands that property remain fluid

Case File: Forensic Analysis

🔬 REGISTRY FILE: CLINICAL PATHOLOGY

The Artifact: The Backdated Minute

The Intent: To focus on business growth and defer 'administrative trivia' to the end of the financial year

The Reality: 'Tax Trap', where the failure to document a decision before the legal deadline results in the forfeiture of all structural tax benefits

Pathology: This is a failure of the Steward Archetype where the brain's 'Momentum Centre' ignores 'Regulatory Finality', the individual treats legal deadlines as 'suggestions', failing to realise that in the eyes of the tax office, an undocumented decision is a non-existent decision

The Legal Reality:  Under Australian Tax Law (Section 95 and 101), a trustee must 'resolve' to distribute income before the end of the financial year: if there is no written record of this resolution by June 30, the income is taxed at the top marginal rate plus the Medicare levy in the hands of the trustee

🟢 ARCHITECTURAL PROTOCOL: SYSTEMIC FIX

The Antidote: The Governance Calendar Protocol: move from 'Year-End Reactivity' to 'Structural Compliance' by implementing a mandatory June 15 governance review where all distribution minutes are drafted, signed, and filed before the deadline

The Result: You transition from 'Regulatory Vulnerability' to 'Structural Compliance': you ensure your hard earned profits stay within your family instead of funding a tax penalty

The Sobering Script: 'I read about 'The Missing Minute'. A business owner lost $450,000 in tax penalties because he did not sign his trust minutes before June 30 and the ATO wiped out all his benefits. I do not want to work this hard just to give half the profit back to the government because of a missing signature. Let's look at the 'Manual' and make sure our compliance calendar is set so we never miss a 'Midnight Deadline' again'

Sorry, this website uses features that your browser doesn’t support. Upgrade to a newer version of Firefox, Chrome, Safari, or Edge and you’ll be all set.